Does Homeowners Insurance Cover Water Damage? What's Covered and What Isn't
Quality 1st Restoration
The short answer
Usually, if the water damage was sudden and accidental, like a pipe that burst. Homeowners insurance generally won't pay for gradual leaks, poor maintenance, flooding or fixing the source itself, such as the pipe or roof. Every policy has limits, and mold is often excluded or capped. Your carrier makes the final call.
Usually, yes, if the water damage was sudden and accidental. A pipe that bursts in the wall overnight or a water heater that fails without warning is the kind of loss a standard homeowners policy is meant to handle. What it generally won’t pay for: slow leaks, maintenance problems, outside flooding or the repair of whatever caused the water in the first place. Mold is often excluded or capped. Your carrier decides the rest based on your policy wording.
That’s the short version. The longer version matters because the parts people assume are covered often aren’t, and the parts they never think about are where the real money goes.
Most of the surprises come down to one thing: policies have limits and exclusions nobody reads until they need them. We run into those gray areas every week, and we have a former insurance agent on staff, so coverage questions aren’t new to us. Here’s the plain version of what a standard policy does and doesn’t do.
Does homeowners insurance cover water damage?
Usually, but only the right kind. A standard homeowners policy is built around water damage that’s sudden and accidental. A pipe bursts inside the wall and soaks your ceiling. A water heater quits with no warning. That’s the classic covered event, and in that situation your insurer will typically pay to dry the structure and put it back together. (1)
What most owners don’t realize is that coverage comes with limits, and some things get denied outright. Your policy pays up to a set dollar amount. Some causes fall outside it entirely. So “yes, water damage is covered” is true and misleading at the same time. The better question is which water damage.
Does insurance cover the source of the water damage?
This is the big one, and it catches almost everybody off guard. Usually, no. Insurance may pay to clean up and repair the damage the water caused. It usually won’t pay to fix the thing that caused it.
Say a roof leak lets water into your house. A standard policy will often cover the wet drywall, insulation and flooring. The roof itself? You’ll most likely pay for that out of pocket. Plumbing works the same way. If a failed pipe or fitting is the culprit, fixing the pipe is typically on you, even when the water damage it caused is covered. The exact wording of your policy matters, and every claim gets decided on its own facts, but that pattern holds far more often than not.
Here's the sentence to remember: insurance may cover the damage but not the cause. It will often pay to dry your house and put the drywall back. It usually will not pay to fix the pipe or the roof that soaked it. That surprises people every single time.
That gap is why the company you call matters. The wrong moves in the first day or two, like mislabeling the cause, skipping documentation or letting the damage spread, can turn a covered claim into a fight. A crew with real insurance claim experience helps you sort out what the policy is likely to pay for and what it isn’t, before you’re in too deep to change course.
Does homeowners insurance cover water damage from a leak?
It depends on the kind of leak. A sudden one, like a supply line that lets go all at once, is generally treated like any other sudden and accidental loss and is usually covered. A gradual leak is different. Water that seeps behind a wall or under a sink for weeks or months is almost always excluded because insurers treat it as a maintenance problem, not an accident. (1)
That’s why documentation and speed matter so much. The longer water sits, the more a slow drip looks like neglect on paper, even if you had no way of seeing it. A leak inside a wall cavity can run for weeks before a stain shows up on the surface. By then the adjuster is looking at rotted framing and asking why nobody caught it sooner.
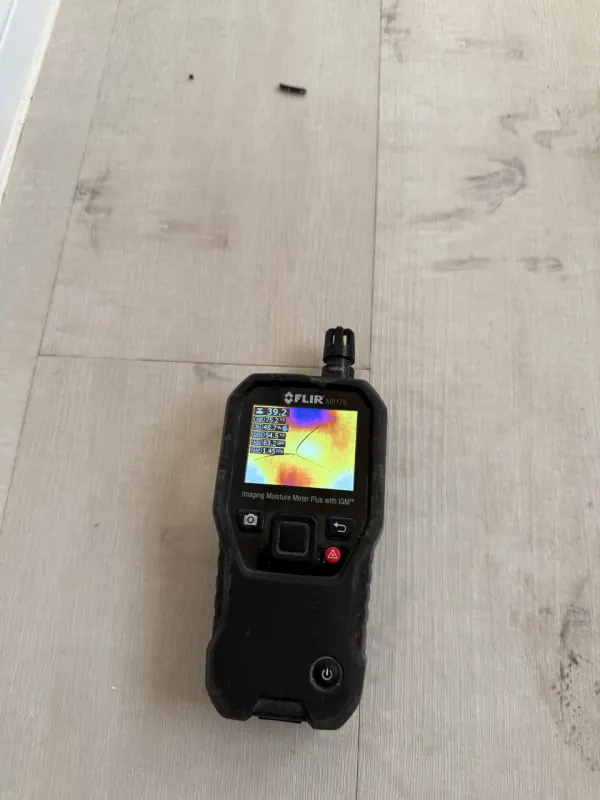
When we scope a job, part of the work is figuring out what actually happened and writing it down. Moisture readings, photos and a clear cause help show this was a hidden failure and not deferred maintenance. Whether that gets paid is still your carrier’s decision, but it gives them the facts. For how leaks turn into damage, our guide to the different types of water damage walks through the categories adjusters use.
Is flood damage covered by homeowners insurance?
Almost never. Flooding is not covered by a standard homeowners policy. Rising water from outside, whether that’s storm runoff, an overwhelmed wash or water coming in at ground level, falls outside the policy and needs separate flood insurance, typically through the National Flood Insurance Program. (2)
"Water damage caused by a flood is not covered under a standard homeowners insurance policy. To be covered for flood damage, you need a separate flood insurance policy."
Insurance Information Institute (1)The policy cares about where the water came from. A pipe bursting inside your home is a plumbing event and usually covered. Water rising into your home from outside is a flood and usually isn’t. Same puddle on the floor. Completely different coverage.
Does homeowners insurance cover mold?
Often not, and people get burned on this one too. Mold is one of the most commonly denied or capped items on a water claim. Some policies exclude it completely. Others cover it only when it comes directly from a covered event, and even then cap the payout at a low limit. (3)
The frustrating part is that speed prevents most of it. Mold can start growing on wet materials within 24 to 48 hours. So the same delay that makes a leak look like neglect also gives mold time to take hold, and then the insurer can point to that delay as a reason to deny the mold part. If growth has already started, you’re probably looking at mold removal alongside the water cleanup, and it pays to find out early how your policy treats it.
The hidden costs, and how to protect yourself
Put it all together and a few things stand out. Your deductible comes off first, so on a smaller loss the check can be thin. The source repair, meaning the roof, pipe or failed valve, is usually yours to pay. That’s a roofer’s or plumber’s job, not ours. Mold may be limited or excluded depending on how your policy is written. And you have a duty to mitigate. You’re expected to stop the water and keep the damage from spreading right away, not wait around for an adjuster. Sitting on the problem to “let insurance handle it” is one of the fastest ways to get a claim reduced.
None of this means you shouldn’t file. It means you should go in knowing what’s likely covered so nothing blindsides you. We document the cause correctly and handle the cleanup and repair in a way that gives the adjuster a clean record to work from. If the damage traces back to your roof, our roof leak water damage crew can point out what typically falls outside a policy before you commit to anything. For costs, see our breakdown of what water damage restoration actually costs.
References
- Insurance Information Institute, "Water Damage: What's Covered; What's Not." https://www.iii.org/press-release/water-damage-whats-covered-whats-not-111809
- FEMA / National Flood Insurance Program, FloodSmart. https://www.floodsmart.gov/
- U.S. Environmental Protection Agency, "Mold Cleanup in Your Home." https://www.epa.gov/mold/mold-cleanup-your-home
If you’re looking at water damage in Henderson or anywhere in the Las Vegas Valley and aren’t sure what your policy covers, start at our water damage restoration hub or call or text us at 888-453-3591. We answer 24/7, and we’ll help you figure out the next step.
Water still spreading? Every hour it sits, the repair gets bigger.
Quality 1st Restoration answers 24 / 7 / 365 across Henderson and the Las Vegas Valley.
888-453-3591