Why Acting Fast Helps Your Water Damage Claim in Las Vegas
Quality 1st Restoration
The short answer
Because most policies cover sudden, accidental water and exclude damage that built up slowly. The longer water sits, the more a fresh leak starts to look like the excluded kind. Reporting fast and documenting early, with photos, moisture readings and the failed part, keeps your claim looking like what it really was.
Acting fast helps because homeowners insurance is mostly built to cover water that shows up suddenly and by accident. It usually excludes damage that developed slowly. Every day water sits, a sudden leak looks a little more like the slow kind. Stop the water, photograph it, keep the failed part and report the loss right away, and the record shows what really happened.
That’s the whole idea. This page is about why speed and documentation matter, so a covered loss doesn’t end up looking like something it wasn’t.
Sudden versus gradual: the line insurers actually draw
Most standard homeowners policies cover the “accidental discharge or overflow of water or steam from within a plumbing, heating, air conditioning, or automatic fire-protective sprinkler system, or from a household appliance.” That’s the classic sudden event. A supply line lets go. A water heater fails. A fitting cracks overnight. What policies generally don’t cover is damage tied to a lack of maintenance or a problem left to develop over time. (Insurance Information Institute: Which disasters are covered by homeowners insurance?)
On paper that line is clean. Standing in front of wet drywall, it isn’t. You often can’t tell by looking whether the water got there last night or has been seeping for two months. And here’s the catch: the longer water sits, the more it can start to resemble the excluded kind of damage, even when the cause really was sudden. Stains spread. Wood swells. Drywall sags. By the time someone photographs it, the pictures may not clearly say “this happened fast” anymore. An adjuster reviewing the file later works from whatever record exists, so the earlier that record starts, the closer it stays to the truth.
Moving fast does two jobs. It limits the damage. It also limits the ambiguity about when and how the damage happened, before that ambiguity gets read against you.
Mold adds a second clock
There’s a physical reason to hurry that has nothing to do with paperwork. The EPA notes that mold can begin growing on wet materials within 24 to 48 hours. (EPA: A Brief Guide to Mold, Moisture, and Your Home) Mold coverage is often limited or excluded on homeowners policies to begin with. If growth has already taken hold by the time anyone inspects, that can complicate how the insurer treats that part of the claim. Two clocks start the moment water hits a surface. One is how the claim will read. The other is what starts growing while nobody’s looking.
A short checklist for the first hours
You don’t need training for any of this. You just need to do it in the right order, before cleanup wipes out the evidence.
- Stop the water if you can do it safely. Shut off the source or the main if you know how. Don’t touch electrical equipment near standing water.
- Photograph and video before you touch anything. Get the source, how far the water spread and the damaged materials. Take wide shots and close-ups before you move belongings or start drying.
- Keep the failed part. A burst supply line, a cracked softener fitting, a valve that quit: set it aside instead of throwing it out. It’s physical proof of what happened.
- Write down when you found it and what you saw. A quick note with a date and time beats a memory of “sometime last week.”
- Call your carrier promptly. Ask for a claim number and what they need from you next. Most policies expect notice without unnecessary delay.
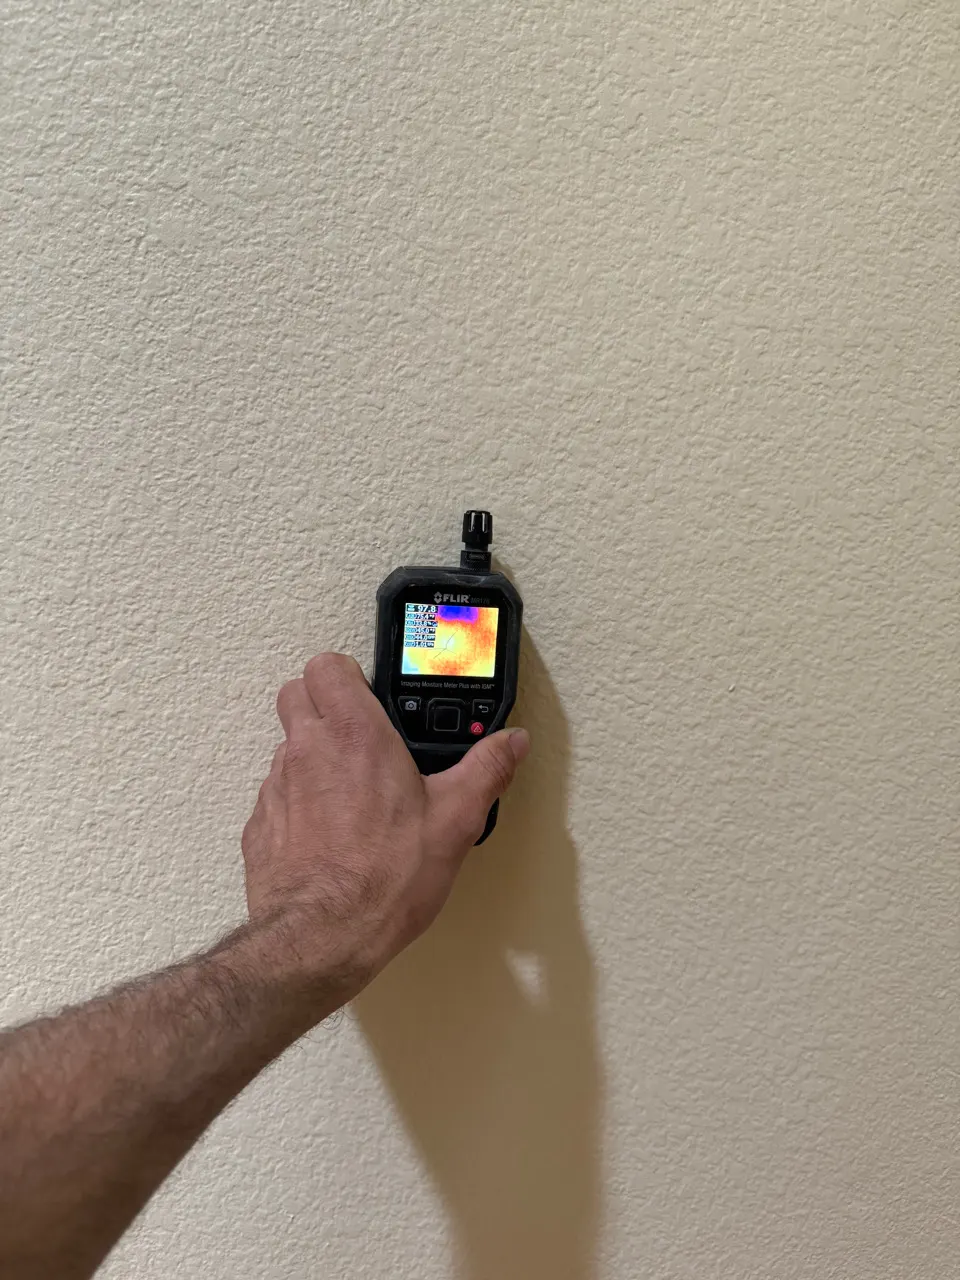
- Get moisture readings on record. A moisture meter or thermal camera shows how far the water traveled and how wet the materials really are. Once everything dries or gets replaced, that evidence is gone.
Why the failed part sometimes matters beyond your claim
There’s another reason to hang on to that part. When a water heater, supply line or appliance fitting fails, insurers sometimes pursue subrogation, which means recovering what they paid from the manufacturer or installer if a defect or bad workmanship caused the loss. Your carrier decides that on its own, from its own investigation. Neither you nor a restoration crew can promise it or predict it. But if the part ends up in a dumpster during cleanup, that door may close before anyone even looks at it. Keeping it costs you nothing, and it isn’t really your option to give up.
Documentation is where restoration and claims meet
This is where a professional response pays off, apart from the drying itself. A proper inspection takes moisture readings across the affected materials, maps where the water went and, when it’s visible, points to where the failure started. Our water damage cleanup and repair crews build that record as part of the job. If you want help pulling it together for your insurer, our insurance claim assistance team can organize the photos, moisture logs and cause-of-loss notes your carrier will likely ask for. None of that guarantees coverage. Your policy and your insurer decide that. A clear, early record just gives the claim its best shot at being judged on the facts.
Still sorting out what your policy covers in the first place, like sudden pipe failures versus long-term leaks, or fixing the source versus the damage it caused? Our guide to does homeowners insurance cover water damage covers that separately from the timing question here.
When water damage in Las Vegas needs a fast, documented response
Speed matters most in the first 24 to 48 hours. That’s also when mold risk climbs and the evidence of “sudden” starts to blur. If you’ve got an active water loss anywhere in the valley, our team provides water damage restoration in Henderson, NV and the surrounding area, with documentation built in from the first visit.
Once you’ve taken reasonable safety steps, call or text Quality 1st Restoration at 888-453-3591. Report the loss to your insurer, keep the failed part, get the moisture readings on record, and let the timeline work for you instead of against you.
This article is general information, not insurance, legal or claims advice. Coverage, exclusions, deductibles, limits and subrogation decisions vary by policy, carrier and the specific facts of a loss. Direct coverage questions to your insurer or licensed agent.
References
Water still spreading? Every hour it sits, the repair gets bigger.
Quality 1st Restoration answers 24 / 7 / 365 across Henderson and the Las Vegas Valley.
888-453-3591